
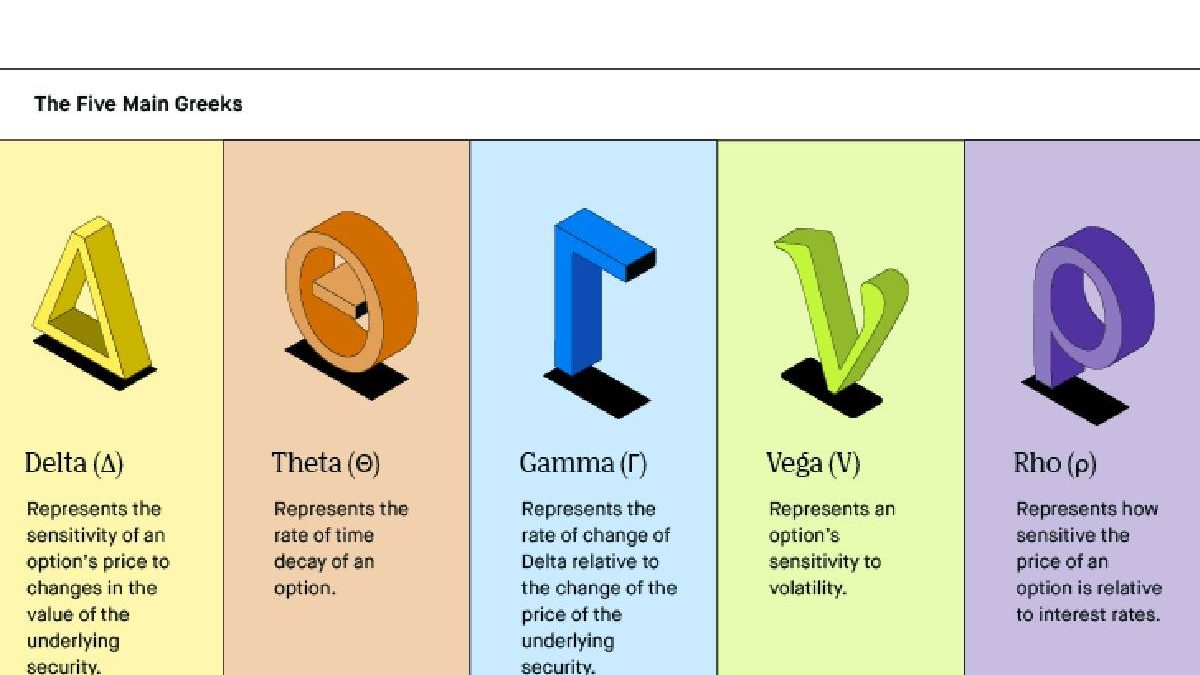
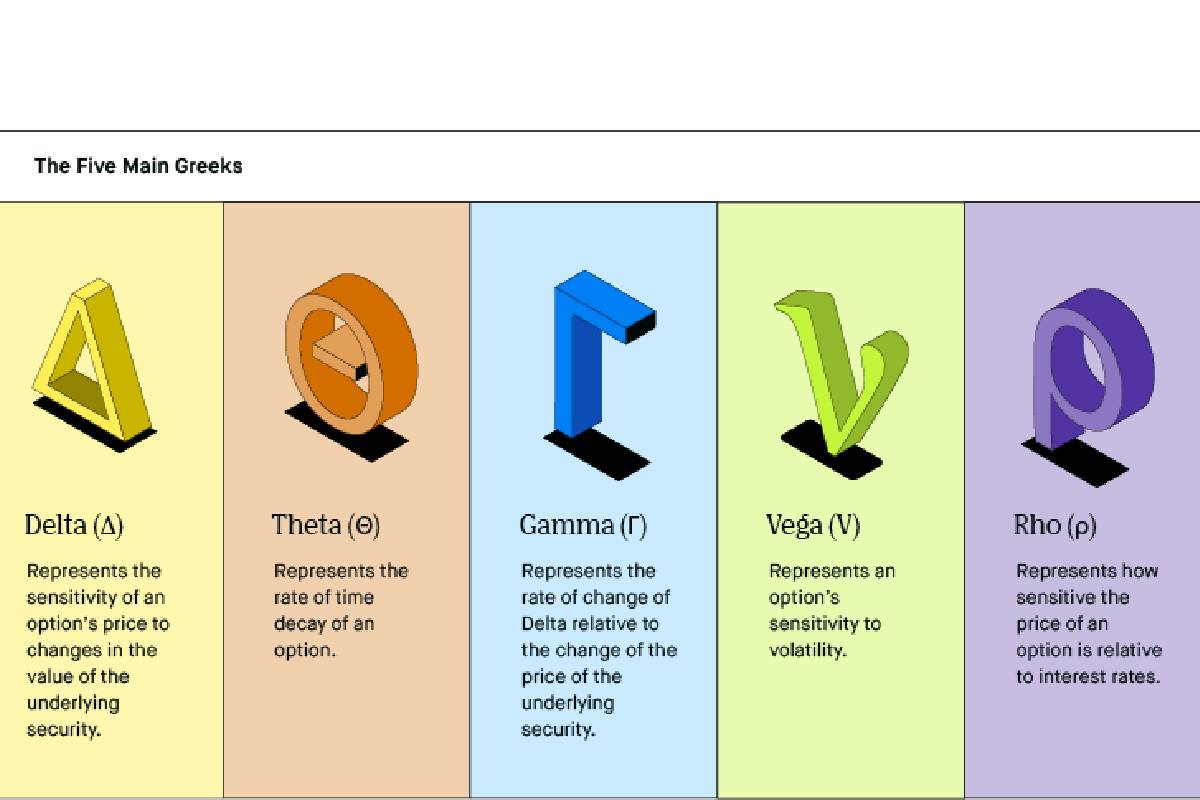
Options trading involves several important measurements that help traders understand how an option’s price may respond to changes in the underlying asset, market volatility, and time. Four of the most widely used measurements are Delta, Gamma, Vega, and Theta. Collectively known as the options Greeks, they provide insights into different aspects of an option’s price sensitivity and risk.
Understanding these concepts can help traders evaluate potential positions, manage exposure, and make more informed decisions. However, the Greeks are estimates based on pricing models and market conditions. They do not guarantee how an option will behave or whether a trade will be profitable.
Table of Contents
Delta: Measuring Sensitivity to the Underlying Asset
Delta measures how much an option’s price is expected to change when the price of its underlying asset moves by one unit, assuming other factors remain unchanged.
For example, if a call option has a Delta of 0.50, its premium may increase by approximately $0.50 when the underlying stock rises by $1. Similarly, a put option with a Delta of -0.50 may increase in value by approximately $0.50 when the underlying stock falls by $1.
Delta is also useful for understanding an option’s directional exposure. Call options generally have positive Delta, while put options generally have negative Delta.
Another important application is delta hedging. Traders use Delta to estimate how much exposure an options position has to movements in the underlying asset.
For example, one standard equity options contract typically represents 100 shares. An option with a Delta of 0.50 therefore has an approximate exposure equivalent to 50 shares. A trader holding 100 shares of a stock could use two put contracts with a Delta near -0.50 each to create an approximate hedge against downward price movements. The actual hedge may change as market conditions and Delta change.
Delta can also provide a rough indication of the probability that an option will expire in the money, although it should not be treated as an exact probability.
Gamma: Understanding Changes in Delta
Gamma measures how quickly an option’s Delta changes when the underlying asset’s price moves. In other words, Delta describes an option’s sensitivity to the underlying asset, while Gamma describes how that sensitivity changes.
Gamma is particularly important for traders who manage positions actively or use delta hedging.
When an option has positive Gamma, its Delta generally increases as the underlying asset’s price rises and decreases as the underlying price falls. Long calls and long puts generally have positive Gamma.
Positive Gamma can benefit long-option positions because the position’s directional exposure can adjust favourably as the underlying asset moves. However, buying options also involves paying a premium, and positive Gamma does not guarantee a profitable trade.
Negative Gamma is generally associated with short-option positions. As the underlying asset moves, the position can become increasingly exposed to unfavourable price changes. Traders with negative Gamma may need to adjust their hedges more frequently, particularly during periods of significant market movement.
Gamma is often higher for options that are close to expiration and near the money. This means their Delta can change rapidly even when the underlying asset moves by a relatively small amount.
Vega: Measuring Sensitivity to Implied Volatility
Vega measures how sensitive an option’s price is to changes in implied volatility. Implied volatility represents the market’s expectation of how much the underlying asset’s price may fluctuate in the future.
Unlike Delta and Gamma, Vega does not primarily measure sensitivity to a price movement in the underlying asset. Instead, it helps traders understand how changes in expected market volatility may affect an option’s premium.
For example, suppose an option has a Vega of 0.10. If implied volatility increases by one percentage point, the option’s price may increase by approximately $0.10, assuming other pricing factors remain unchanged.
Long calls and long puts generally have positive Vega. Their premiums tend to increase when implied volatility rises and decrease when implied volatility falls.
Short-option positions generally have negative Vega. These positions may benefit from falling implied volatility but can become more expensive to close if volatility increases.
Vega is particularly relevant around events that may create uncertainty, such as company earnings announcements, major economic reports, or central bank decisions. Traders should remember that higher implied volatility can make options more expensive, so buying an option before an anticipated event does not automatically lead to a profit.
Theta: Understanding Time Decay
Theta measures how sensitive an option’s price is to the passage of time. It is commonly used to estimate the amount an option’s premium may lose each day as expiration approaches, assuming other pricing factors remain unchanged.
Options have a limited lifespan. As expiration gets closer, there is generally less time for the underlying asset to move enough to make an option profitable. This effect is known as time decay.
Long options generally have negative Theta because their time value tends to decrease as expiration approaches. Short options generally have positive Theta because the passage of time can work in favour of the seller, provided other factors do not create larger losses.
For example, a long option with a Theta of -0.05 may lose approximately $0.05 in value over a day under the assumptions of the pricing model.
Theta does not remain constant throughout an option’s life. Time decay often accelerates as expiration approaches, particularly for at-the-money options. However, the precise effect depends on the option’s strike price, volatility, and other market conditions.
Traders who buy options need to consider whether the underlying asset is likely to move sufficiently before expiration to offset the impact of time decay. Sellers also need to remember that collecting time value involves taking on other risks, including potentially substantial losses from adverse price movements.
What Are Delta, Gamma, Vega, and Theta Used For?
The four Greeks help traders examine different sources of options risk. They are most useful when considered together because a change in one market factor can affect an option’s value while other factors are also changing.
Using Delta to Assess Directional Exposure
Delta helps traders estimate how an option’s value may respond to a movement in the underlying asset.
A higher positive Delta generally means a call option is more sensitive to upward price movements. A more negative Delta means a put option is more sensitive to downward movements.
Traders can use Delta when comparing options with different strike prices and expiration dates. It can also help them estimate the directional exposure of a portfolio containing multiple options and shares.
Using Gamma to Monitor Changing Exposure
Gamma helps traders understand how quickly their Delta exposure may change.
A position with high positive Gamma can experience rapid changes in Delta as the underlying asset moves. This can be useful for long-option strategies, although the premium paid and time decay must also be considered.
For traders with negative Gamma, rapid market movements can increase risk and make position management more challenging. Monitoring Gamma can therefore help traders decide when adjustments or additional risk controls may be necessary.
Using Vega to Evaluate Volatility Expectations
Vega is useful when a trader expects implied volatility to rise or fall.
A trader who expects volatility to increase may consider how positive Vega could benefit a long-option position. Conversely, a trader who expects volatility to decline may examine strategies with negative Vega exposure.
However, volatility expectations can change quickly. Even if the underlying asset moves in the expected direction, a decline in implied volatility may reduce the value of a purchased option.
Cryptocurrency markets can also experience significant price fluctuations, making it important for users to understand volatility and transaction-related risks. Anyone exploring cryptocurrency access should also consider security and provider reliability when looking for a trusted crypto ATM near them.
Using Theta to Evaluate the Cost of Time
Theta helps traders understand how much time decay may affect an options position.
A trader purchasing an option should consider whether the expected price movement is likely to occur before expiration. A trader selling options may seek to benefit from time decay, but must also account for the risk of large movements in the underlying asset.
Understanding Theta is especially important when comparing options with different expiration dates. A cheaper option with a short expiration may have less time to respond to favourable market movements.
How the Four Greeks Work Together
Delta, Gamma, Vega, and Theta provide different perspectives on the same options position. Looking at only one measurement can give an incomplete picture of the risks involved.
Consider a trader purchasing a call option before a major company announcement. Delta helps estimate the option’s sensitivity to the stock price, while Gamma indicates how that Delta may change as the stock moves. Vega shows how a change in implied volatility could affect the premium, and Theta highlights the cost of holding the option as time passes.
Even if the stock rises, the option may not gain as much value as expected if implied volatility falls sharply or time decay offsets part of the price movement.
This is why traders should examine the combined effects of the Greeks instead of relying on a single measurement. They should also consider the option’s premium, strike price, expiration date, liquidity, and the possibility of losing the entire amount invested.
Options can be used for speculation, income strategies, and hedging, but they involve risks that may be unsuitable for some investors. Anyone considering these instruments should understand the contract terms and potential losses before entering a position. Readers exploring broader retirement investment choices may also find it useful to understand tips relating to Gold IRA custodian services when comparing different types of investment accounts and their administrative requirements.
Considering Options Trading Alongside Other Financial Priorities
Options trading is only one part of a broader financial picture. Investors should also consider other financial responsibilities, including family protection and long-term financial security. For self-employed Indians living abroad, understanding NRI term insurance plans that cover self-employed Indians abroad can help them explore suitable protection options alongside their investment decisions.
Final Thoughts
Delta, Gamma, Vega, and Theta are essential tools for understanding options pricing and managing trading exposure. Delta measures sensitivity to the underlying asset’s price, Gamma measures changes in Delta, Vega measures sensitivity to implied volatility, and Theta measures the effect of time decay.
Together, these measurements help traders evaluate potential risks, compare options contracts, and monitor how market conditions may affect their positions. They are not signals that independently determine the best time to enter or exit a trade, but they can provide valuable information when combined with sound research and risk management.
Successful options trading requires more than understanding the Greeks. Traders should develop a clear strategy, assess their financial circumstances, and avoid risking money they cannot afford to lose.